Top African Fintech Companies in 2026: Nigeria to Kenya
The leading African fintech companies in 2026, from M-Pesa, OPay and Moniepoint to Wave, Tyme and Yellow Card, with dated users, valuations and funding.

Key takeaways
- African tech raised about $4.1 billion in 2025 by Partech's count, with record debt of $1.6 billion, while fintech's share of equity fell.
- OPay processed $358 billion in 2025 with 39.3 million monthly users and is preparing a New York listing, while M-Pesa had 43.69 million active users in Kenya.
- The leaders are moving from cheap transfers into lending and banking licences, which is where their revenue and regulatory risk now sit.
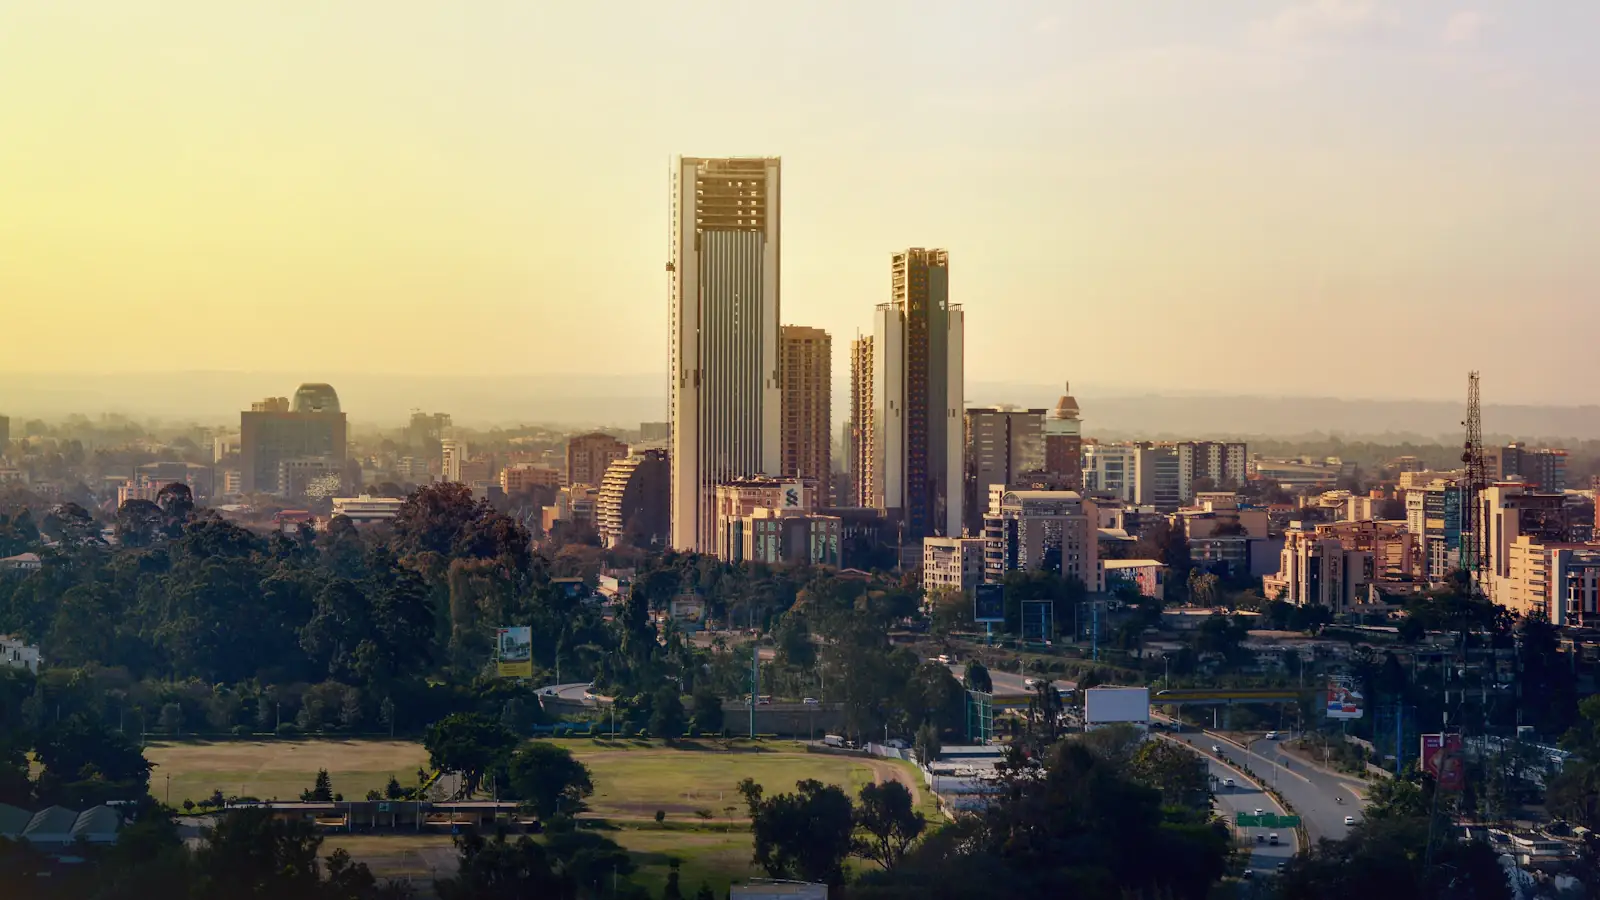
A pharmacist in Abidjan's Treichville market pays her wholesaler from her phone at the end of each week. The transfer costs her a flat 1%, and taking cash out at an agent costs nothing. Older telecom wallets charged several times that. That gap, between what African money used to cost and what a handful of companies now charge, is where most of the continent's fintech value has been built. It is also why the list of companies that matter in 2026 looks very different from the list of companies that raised the most in 2021.
How we chose. This is a list of 13 African fintech companies grouped by what they do rather than ranked one to thirteen. We looked at scale (users, transaction value, revenue), growth, licences held, funding and valuation, and product breadth, using figures each company or its investors disclosed, as of October 2026. Where no recent number is verifiable, we say so. Global card networks and banks are left out.
How much money went into African fintech in 2025?
African tech companies raised about $4.1 billion in 2025, up 25% on 2024, according to Partech Africa, with fintech taking $769 million of the $2.4 billion in equity. Briter's separate count put total disclosed funding at $3.8 billion, up 32%, with fintech again the most funded sector. The headline story of 2025 was debt, not equity: lenders, not venture funds, financed the biggest growth.
The 2025 Partech Africa Tech VC report counted 570 transactions, with debt rising 63% to a record $1.6 billion and making up 41% of all capital deployed, up from 31% a year earlier. Fintech's slice of equity shrank as cleantech, health and enterprise software grew; investors are no longer writing payments cheques on growth alone.
Briter's Africa Investment Report 2025 split the money by country: South Africa took 32% of funding, Kenya 29%, Egypt 15% and Nigeria just 8%. Nigeria had its lowest share since 2019 but the largest number of deals. Nigerian fintech is still the busiest market on the continent, but its rounds have got smaller in dollar terms. Kenya, by Partech's count, led the continent with $1.04 billion and four of the year's nine megadeals.
Which mobile money companies lead African fintech in 2026?
Mobile money remains the largest part of African fintech in 2026. M-Pesa, run by Safaricom in Kenya and Ethiopia and by Vodacom elsewhere, is the biggest by users and value moved, and Wave is the fastest-growing challenger in francophone West Africa. For the history, see our guide to M-Pesa and mobile money.
M-Pesa (Safaricom, Kenya)
Safaricom's results for the year to 31 March 2026 put active M-Pesa users in Kenya at 43.69 million, up 18%, and M-Pesa revenue at Ksh 182.73 billion, up 13.4%, according to HapaKenya's breakdown of the results. M-Pesa now earns 45.6% of Safaricom's Kenya service revenue, which makes the telco as much a payments company as a phone company. In Ethiopia, M-Pesa reached 5.2 million 90-day customers, more than double a year earlier.
M-Pesa (Vodacom Group)
Vodacom, a major shareholder in Safaricom, reported 103.0 million financial services customers for the year to 31 March 2026, a figure that counts Safaricom on a 100% basis, and said the transaction value it processed reached $525.6 billion, up 16.6%, according to its FY2026 results announcement. Because Safaricom is included, these group numbers should not be added to the Kenyan figures above. Its other markets include Tanzania, Mozambique, Lesotho and Egypt.
Wave (Senegal)
Wave built its business on a flat 1% transfer fee and free cash-in and cash-out, undercutting telecom wallets that charged 5% to 10%. In June 2025 it raised about $137 million (EUR 117 million) in debt led by Rand Merchant Bank, with British International Investment, Norfund and Finnfund, as Launch Base Africa reported. At the time it had more than 20 million monthly active users, about 150,000 agents and operations in eight countries. Its last disclosed valuation was $1.7 billion, set in 2021.
Who are the biggest fintech companies in Nigeria in 2026?
Nigeria's largest fintech companies in 2026 are OPay and Moniepoint by users and transaction value, with Paystack and Flutterwave leading merchant payments. OPay processed $358 billion in 2025 and is preparing a New York listing; Moniepoint says it handles more than $250 billion a year. Nigeria has the most fintech deals in Africa even though its share of funding has fallen.
OPay
OPay is the largest consumer fintech in Nigeria by the numbers it has disclosed. Its gross transaction value more than doubled to $358 billion in 2025, monthly active users rose 57% to 39.3 million, and revenue grew 161% to $536.3 million, according to Nairametrics. It turned an operating profit of $107.1 million. Nigeria supplied 88.1% of revenue, with Indonesia and Egypt making up most of the rest. Citigroup, Deutsche Bank and JPMorgan are managing a planned NYSE listing at a targeted valuation of about $4 billion.
Moniepoint
Moniepoint's products range from handheld point-of-sale devices for cash deposits, withdrawals and card payments to a personal banking app. In October 2025 it raised $90 million to complete a $200 million Series C at a valuation of about $1 billion, Semafor reported. It says it serves more than 10 million businesses and individuals and processes more than $250 billion a year. In April 2025 it launched UK-to-Nigeria remittances, its first step outside domestic payments.
Paystack
Paystack, bought by Stripe in 2020 for $200 million, serves about 300,000 businesses, mostly in Nigeria. In early 2026 it took over Ladder Microfinance Bank, giving a sister company, Paystack MFB, its own banking licence, according to Launch Base Africa. The move followed a reported N250 million Central Bank of Nigeria fine over its Zap transfer app, which regulators said had gone beyond its deposit-taking permissions. Bank transfers made up 66% of its Nigerian volume in 2024.
Flutterwave
Flutterwave is one of the most widely used pan-African payment processors for merchants selling across borders. Founder Olugbenga Agboola wrote in June 2026 that it had passed 1 billion transactions and more than $40 billion in payments since inception, and had won new licences in Senegal, Zambia and Cameroon during the year, per Nairametrics. In January 2026 it bought the Nigerian open-banking start-up Mono in an all-stock deal, adding bank-data access and account-to-account payments.
Which digital banks and lenders are scaling outside Nigeria and Kenya?
Outside Nigeria and Kenya, the fastest-scaling African fintechs in 2026 are digital banks and lenders in South Africa and Egypt. Tyme Group, which runs GoTyme Bank in South Africa and the Philippines, reached a $1.5 billion valuation after Nubank led its Series D, and Egypt's MNT-Halan was valued at $1.4 billion in a June 2026 round led by Al Ahly Capital.
GoTyme Bank (Tyme Group, South Africa)

Tyme Group raised a $250 million Series D in December 2024 at a $1.5 billion valuation, with Brazil's Nubank putting in $150 million, according to FinTech Futures. That remains its latest disclosed valuation. In April 2026 the South African Reserve Bank published the renaming of TymeBank as GoTyme Bank, matching its Philippine sister bank, and the group then had more than 15 million customers, over 10 million of them in South Africa, Financial Afrik reported. It is one of the few African digital bank models running at scale in Asia.
MNT-Halan (Egypt)

MNT-Halan combines consumer and small-business lending with payments. Its latest round, led by Al Ahly Capital, the investment arm of the National Bank of Egypt, valued it at $1.4 billion at first close in June 2026, Wamda reported. It also operates in Turkiye and entered the UAE in 2024.
Who builds Africa's cross-border and stablecoin payment rails?
Africa's cross-border rails in 2026 are built by a small group: Onafriq connects mobile wallets and bank accounts across borders, LemFi serves the diaspora sending money home, and Yellow Card runs a licensed stablecoin on- and off-ramp. Chipper Cash spans app-based transfers and newer stablecoin integrations.
Onafriq
Onafriq runs the plumbing that lets a wallet in one country pay a wallet or bank account in another. When it marked 15 years in June 2025 it said its network could reach 961 million registered mobile wallets and 464 million bank accounts across more than 2,000 corridors, per HapaKenya.
LemFi
LemFi, based in London, serves African and Asian migrants sending money home. Its $53 million Series B in January 2025 was led by Highland Europe, and it reported about $1 billion in monthly payment volume and 1 million active users, according to The Condia. It operated in 27 send-from markets and 20 receiving countries and was buying a licensed Irish firm to passport across the EU.
Yellow Card
Yellow Card is one of the longest-running stablecoin on- and off-ramps on the continent. It received a crypto asset service provider licence in South Africa in late 2024, had raised $33 million, and said it had processed more than $3 billion since 2016 across 20 African countries, per TechCabal.
Chipper Cash
Chipper Cash, a cross-border transfer app that raised a $100 million Series C during the last funding boom, said in December 2025 that it had seven million customers across nine African countries, when it announced a partnership to run stablecoin payments over Stable, a USDT-focused blockchain, per its own announcement. It was also among the wallets that integrated PayPal's PYUSD stablecoin on the Stellar network in September 2025, per the Stellar Development Foundation.
How do Africa's leading fintech companies compare?
Compared side by side in 2026, OPay and M-Pesa lead on users and transaction value, Moniepoint and OPay lead Nigeria, and Tyme and MNT-Halan carry the highest disclosed valuations outside Nigeria. Metrics differ between companies, so read across rows with care.
| Company | Base | What it does | Latest dated metric |
|---|---|---|---|
| M-Pesa (Safaricom) | Kenya | Mobile money | 43.69M active users, FY to Mar 2026 |
| M-Pesa (Vodacom) | South Africa | Mobile money, group | 103.0M financial services customers incl. Safaricom; $525.6B processed, FY to Mar 2026 |
| OPay | Nigeria | Wallet, payments, loans | $358B GTV, 39.3M MAU, 2025 |
| Moniepoint | Nigeria | POS, business and personal banking | ~$1B valuation, Oct 2025 |
| Paystack | Nigeria | Merchant payments | ~300,000 businesses, Jan 2026 |
| Flutterwave | Nigeria / US | Payments processing | $40B+ processed since launch, Jun 2026 |
| Wave | Senegal | Mobile money | 20M+ MAU, Jun 2025 |
| Tyme Group | South Africa | Digital bank (GoTyme) | 15M+ customers, Apr 2026; $1.5B valuation, Dec 2024 |
| MNT-Halan | Egypt | Lending, payments | $1.4B valuation, Jun 2026 |
| Onafriq | Pan-African | Cross-border wallet hub | 961M wallets reachable, Jun 2025 |
| LemFi | UK | Diaspora remittance | ~$1B monthly volume, Jan 2025 |
| Yellow Card | Pan-African | Stablecoin on/off-ramp | $3B+ processed since 2016, Nov 2024 |
A worked example shows why scale alone is not the full story. Divide Safaricom's M-Pesa revenue of Ksh 182.73 billion by 43.69 million active users and each user generated about Ksh 4,182 in the year. Do the same for OPay, $536.3 million over 39.3 million monthly users, and the figure is about $13.65 per user. Wave's model sits at the other end: on a transfer equal to $100, its 1% fee is $1, against the $5 to $10 that the same transfer cost on older telecom wallets. Cheap transfers win users; lending, merchant fees and float are what pay the bills. Hence OPay's 285% jump in new loans in 2025.
In African fintech the transfer is the hook. The licence and the loan book are the business.
What does this mean for Nigeria and Kenya?
For Nigeria and Kenya in 2026, the lesson is that the leaders are profitable incumbents rather than fresh start-ups. Both markets are led by companies that moved from payments into lending and banking.
In Kenya, a fintech either plugs into M-Pesa or targets a niche it ignores, and the sharpest growth is now in Ethiopia. For how these systems connect, see our report on payments in Africa in 2026.
In Nigeria, the regulator is the swing factor. Paystack's fine over Zap, the push by fintechs to buy microfinance banks and Yellow Card's wait for an SEC decision all point the same way: the Central Bank of Nigeria and the SEC want fintechs inside the regulatory perimeter, holding licences that match what they actually do. Diaspora flows matter too: Moniepoint's UK corridor and LemFi target the same money that our analysis of the cost of sending money to Africa shows is still among the most expensive in the world to move.
What to watch next in African fintech
The next six months will test whether African fintech can reach public markets. OPay's planned NYSE listing, MNT-Halan's second close and Partech's 2026 report, due in early 2027, are the dates that matter. Stablecoin licensing in Nigeria and South Africa will decide how quickly dollar balances spread inside African apps.
- OPay's listing, expected later in 2026. A successful float near the reported $4 billion target would be one of the largest African fintech listings to date and could reset valuations for Moniepoint and others.
- MNT-Halan's second closing. Still pending as of June 2026; its size will show how much Gulf and Egyptian bank capital is willing to back fintech lending.
- Partech's 2026 report, likely January 2027. The key number is whether debt keeps growing as a share of capital. If it does, expect more fintechs to look like lenders.
- Stablecoin rules. Yellow Card's Nigerian application and further South African CASP licences will decide whether stablecoin balances stay a niche or become a standard feature. Our stablecoin companies to watch and fintech start-ups to watch lists track the wider field.
This list is editorial research, not investment advice or an endorsement of any company. Company figures are as reported by the linked sources and may use different definitions of users and volume.
Frequently asked questions
What is the biggest fintech company in Africa in 2026?
By users and value moved, M-Pesa is the largest: Vodacom reported 103.0 million financial services customers, including Safaricom, and $525.6 billion of transaction value processed in the year to March 2026. Among independent fintechs, OPay is the largest by disclosed numbers, with $358 billion processed in 2025.
Which are the top fintech companies in Nigeria?
By disclosed scale, OPay and Moniepoint lead Nigeria, with OPay at 39.3 million monthly users in 2025 and Moniepoint valued at about $1 billion in October 2025. Paystack and Flutterwave lead merchant payments.
How much funding did African fintech raise in 2025?
Partech counted $769 million of equity funding for African fintech in 2025, within $4.1 billion of total tech funding including debt. Briter separately named fintech the most funded sector of 2025.
Which country in Africa raised the most startup funding in 2025?
Kenya ranked first in Partech's 2025 report with $1.04 billion, while Briter's count put South Africa slightly ahead with 32% of funding against Kenya's 29%. The two trackers use different methods.
Sources and further reading
- Partech: 2025 Africa Tech VC Report
- Briter: Africa Investment Report 2025
- HapaKenya: Safaricom FY2026 results
- Vodacom Group: Reviewed annual results for the year ended 31 March 2026
- Financial Afrik: TymeBank completes its rebranding
- Nairametrics: OPay transactions reach $358 billion
- Semafor: Moniepoint raises $90m
- FinTech Futures: Tyme Group Series D led by Nubank
- Wamda: MNT-Halan reaches $1.4 billion valuation
- Nairametrics: Flutterwave passes 1 billion transactions
This article is for general information and is not financial, legal or tax advice. Figures are as reported by the sources above at the time of writing.