How Crypto and Stablecoin Cards Work: Issuers, Networks, Fees, Rules
A plain guide to crypto and stablecoin debit cards: who issues them, how Visa and Mastercard fit in, what happens at checkout, the fees and the rules in 2026.

Key takeaways
- A crypto card is a normal Visa or Mastercard debit or prepaid card whose balance is funded by stablecoins or crypto rather than a bank account.
- Annualised crypto card spending passed $18 billion by early 2026, and Visa reports more than 160 stablecoin-linked card programmes live.
- Total cost depends on conversion spreads, FX rates, onchain fees and card charges, and spending crypto can be a taxable disposal in many countries.
A barista in Lisbon taps a card, the terminal beeps, and a few cents of euro land in the cafe's account the next day. Nothing about that moment tells you the customer was spending dollar stablecoins held in a crypto wallet. That invisibility is the whole design of the crypto card, and it explains why the product has quietly become one of the busiest corners of the digital asset economy.
The card is ordinary. The account behind it is not
Strip away the branding and a crypto card is a regular debit or prepaid card running on Visa or Mastercard. The merchant sees a normal card transaction in local currency. What differs is the funding source. Instead of a checking account at a bank, the balance sits in stablecoins or other crypto assets, either with a custodial provider or in the customer's own wallet.
Several companies sit in the chain. A card programme usually involves an issuing bank or licensed principal member of the card network, a programme manager that runs the app and the customer relationship, a processor that handles authorisations, and a crypto custodian or wallet provider holding the assets. Some infrastructure firms bundle several of those roles. Rain, for example, is a Visa principal member, and The Block reported in September 2026 that it had financed roughly $2 billion of card settlement through an onchain credit facility since 2023.
What happens in the two seconds at the till
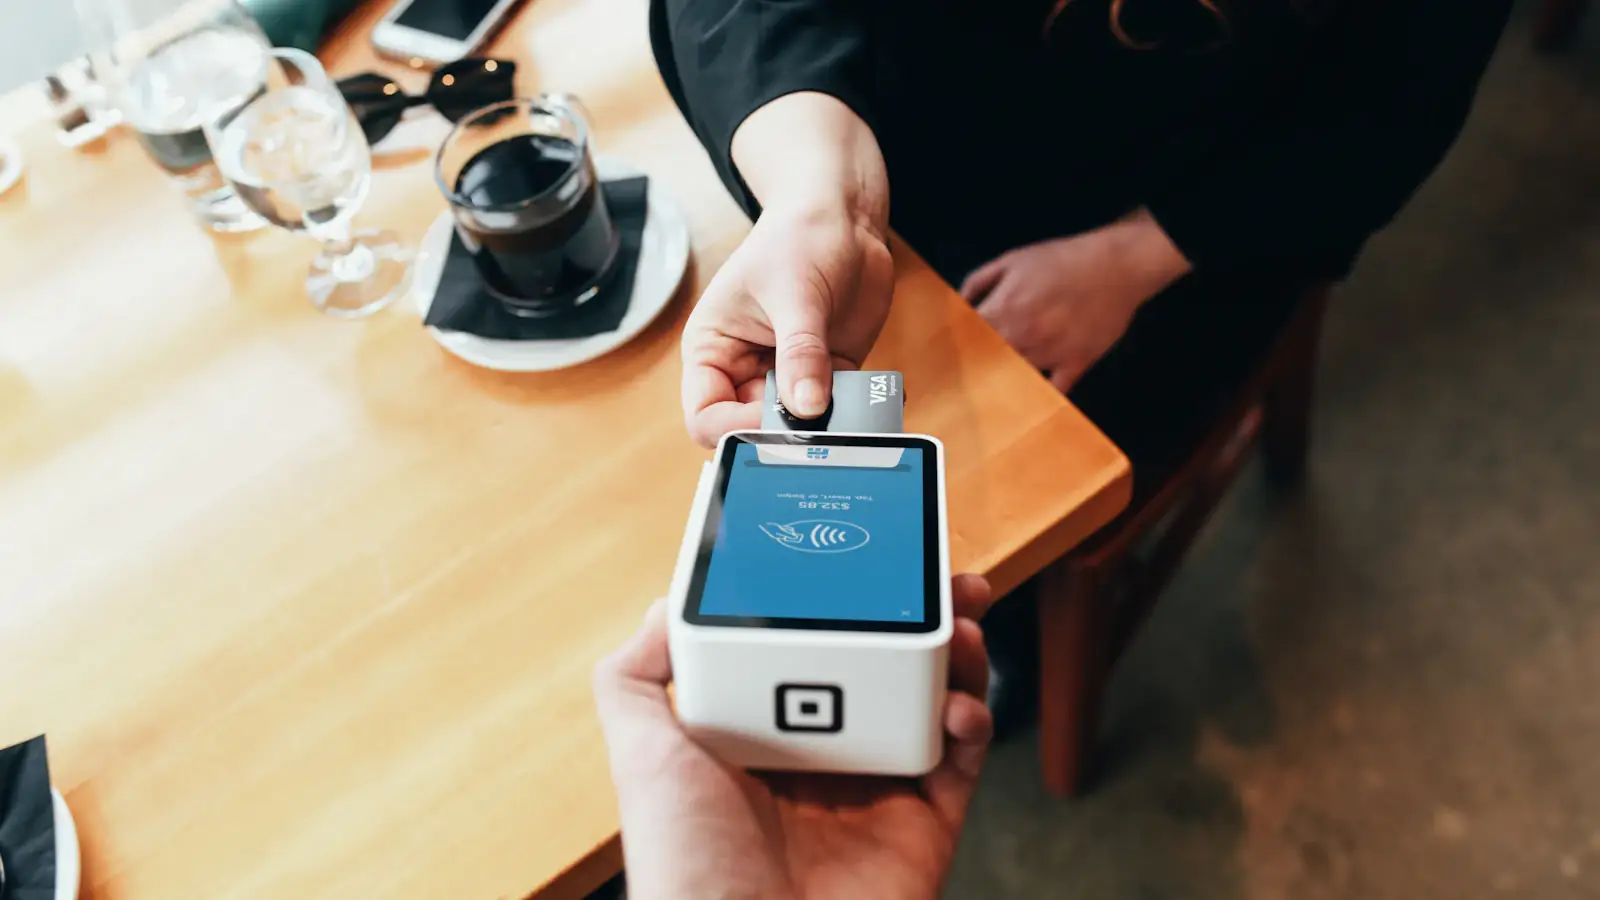
When the card is tapped, the network sends an authorisation request to the issuer's processor, just as it would for any debit card. The processor checks whether the linked crypto balance can cover the amount at the current rate. If it can, the matching amount of stablecoin or crypto is reserved or sold, the authorisation is approved and the merchant gets paid in local currency through normal card settlement.
There are two common models:
- Custodial cards. The provider holds your assets and converts them at the moment of purchase. This is fast and simple, but you are trusting a company with your money.
- Self-custodial cards. Funds stay in your own wallet, and you approve a smart contract that lets the card programme pull a set amount when you spend. You keep control, but you take on the job of protecting your keys. We cover the trade-off in more detail in our guide to self-custody versus custodial wallets.
Behind the scenes, the card programme still owes the network money every day. Historically that meant converting crypto into dollars or euros to settle. Increasingly, networks accept settlement in stablecoins directly. Visa said its stablecoin settlement had passed a $20 billion annualised run rate, more than 15 times the year before, according to The Block in September 2026.
Source Artemis via The Defiant, January 2026; Visa via The Block, September 2026.
How big has this become?
Card spending is one of the few stablecoin use cases where ordinary consumer behaviour shows up clearly in the data. Analytics firm Artemis estimated in January 2026 that annualised crypto card spending had passed $18 billion, putting it within reach of peer-to-peer stablecoin transfers, as reported by The Defiant.
The smaller, fully onchain cards show the same curve. Dune Analytics data cited by Cointelegraph showed monthly net spend across six self-custodial Visa cards rising from $14.6 million in January 2025 to $91.3 million in December, with the EtherFi card alone accounting for $55.4 million over the year. Visa told investors it had more than 160 stablecoin-linked card programmes live in its fiscal second quarter of 2026.
Mastercard has been moving too. In March 2026 it launched a Crypto Partner Program with more than 85 companies, including exchanges, wallet providers and stablecoin issuers, aimed at settlement, payouts and consumer payments.
Where the fees hide
Crypto cards rarely advertise a single headline charge, because the cost is spread across several layers. When comparing programmes, look at each of these separately:
- Conversion spread. If you hold bitcoin or ether, the card sells it at a rate that may sit above or below the market price. With dollar stablecoins this spread is usually thin for dollar purchases.
- Foreign exchange. Paying in euros from a dollar stablecoin balance involves a currency conversion, and the rate used matters as much as any stated fee. Our explainer on the mid-market rate shows how to spot the markup.
- Network and onchain costs. Self-custodial cards may pass on blockchain transaction fees for top-ups or settlement.
- Card fees. Issuance, monthly, inactivity and ATM charges vary widely.
Rewards can offset some of this, but cashback paid in a volatile token is not the same as cashback paid in dollars.
A crypto card is only as cheap as its worst conversion, so price the whole journey, not the advertised fee.
The rules now apply to the card, and the coin
Because the card leg runs on Visa and Mastercard, it is regulated like any card product: the issuer needs a bank charter or e-money licence, and the programme must run identity checks and anti-money-laundering controls. What changed in 2025 and 2026 is that the stablecoin leg now has its own rulebook in the largest markets.
In the United States, the GENIUS Act became law on 18 July 2025, requiring payment stablecoin issuers to hold at least one dollar of permitted reserves for every dollar issued and barring them from paying interest to holders, according to the Congressional Research Service. In the European Union, MiCA treats euro and dollar stablecoins as e-money tokens; by July 2026, 21 authorised issuers across 12 member states were issuing 35 such tokens. Our overview of GENIUS and MiCA goes deeper.
Tax is the piece most users underestimate. In many countries, swapping crypto for goods is treated as a disposal, so a card purchase funded by bitcoin can create a taxable gain or loss. Spending a dollar stablecoin usually produces little or no gain, but the record-keeping obligation can still apply.
Our view: the card is a bridge, not the destination
Crypto cards succeed because they ask nothing of the merchant. That is also their limit. Every purchase still passes through interchange, network fees and an issuing bank, so the cost structure looks a lot like the card system it rides on. The more interesting shift is happening underneath, as networks start settling in stablecoins and programme managers fund cards from onchain credit. If that plumbing keeps maturing, the card may end up as the familiar front end for money that moves very differently behind the counter.
This article is for information only and is not financial or tax advice. Card features and fees change often; check current terms with any provider.
Frequently asked questions
How does a crypto debit card work?
The card runs on Visa or Mastercard like any debit card, but its balance is held in stablecoins or crypto. When you pay, the provider converts the needed amount and the merchant receives local currency.
Are crypto cards regulated?
Yes. The card is issued by a licensed bank or e-money institution and must follow card network and anti-money-laundering rules, and stablecoins themselves now fall under laws such as the US GENIUS Act and the EU's MiCA.
Is spending crypto with a card taxable?
In many countries, using crypto to pay for goods counts as a disposal, which can create a gain or loss. Spending dollar stablecoins usually creates little gain, but records may still be required, so check local rules.
Sources and further reading
- The Block: Visa stablecoin settlement tops $20 billion annualized run rate
- The Defiant: Crypto cards rival stablecoin transfers as spending tops $18 billion
- Cointelegraph: Net spend on Visa crypto cards increased by 525% in 2025
- Congressional Research Service: Overview of the GENIUS Act of 2025
- Stablecoin Insider: Mastercard launches Crypto Partner Program
- KuCoin News: MiCA fully implemented with 21 EMT issuers
This article is for general information and is not financial, legal or tax advice. Figures are as reported by the sources above at the time of writing.